
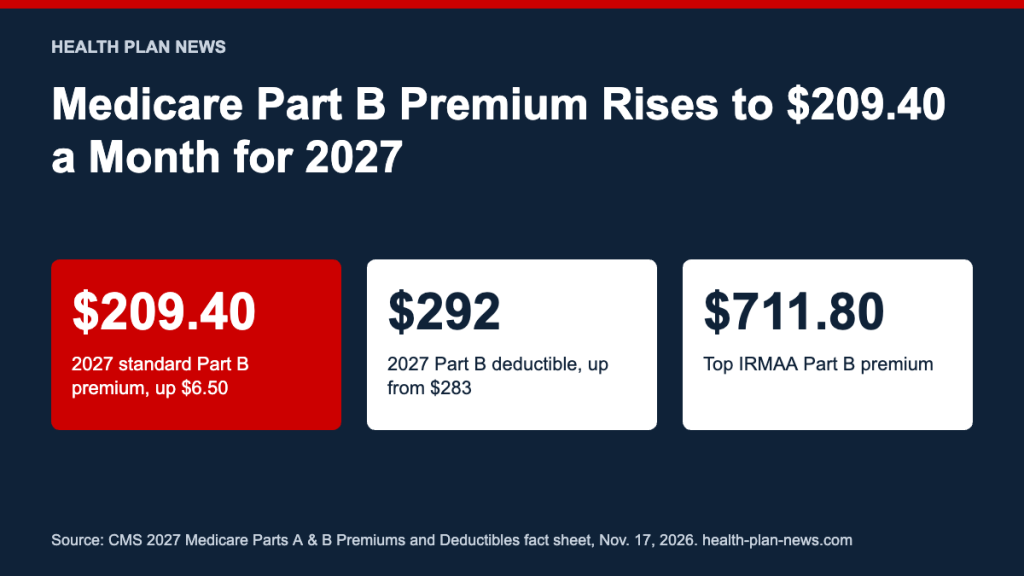
The standard Medicare Part B premium will rise to $209.40 a month in 2027, up $6.50 from $202.90, the Centers for Medicare & Medicaid Services (CMS) announced November 17. The Part B deductible climbs to $292 from $283, and higher earners will pay as much as $711.80 a month under the new IRMAA (Income-Related Monthly Adjustment Amount) brackets.
The 3.2% increase lands almost exactly where the Medicare Trustees projected it, at $209.50, and below the 3.6% cost-of-living adjustment that Social Security announced for 2027. Most retirees should see a net gain in their monthly checks. CMS ties the increase mainly to projected growth in health care spending.
If your 2025 income came close to a bracket line, check where you land now. Our updated 2027 IRMAA brackets guide has the full tables and the Form SSA-44 appeal steps.
2027 IRMAA Brackets
IRMAA applies to individuals with 2025 modified adjusted gross income (MAGI) above $112,000 and joint filers above $224,000, up from $109,000 and $218,000 for 2026. The surcharges add to both Part B and Part D premiums.
- $112,001 to $141,000 single, $224,001 to $282,000 joint: $293.10 for Part B, plus $15.40 for Part D.
- $141,001 to $177,000 single, $282,001 to $354,000 joint: $418.80 for Part B, plus $39.70 for Part D.
- $177,001 to $212,000 single, $354,001 to $424,000 joint: $544.40 for Part B, plus $64.00 for Part D.
- $212,001 to $499,999 single, $424,001 to $749,999 joint: $670.00 for Part B, plus $88.30 for Part D.
- $500,000 or more single, $750,000 or more joint: $711.80 for Part B, plus $96.40 for Part D.
The top two thresholds, $500,000 and $750,000, are fixed by law and did not move.
The brackets have a hard edge. One dollar over a line triggers the full surcharge, so a Roth conversion or home sale in 2025 can cost a retiree more than $1,000 a year in 2027 premiums. CMS says about 9% of Part B enrollees pay IRMAA.
Part A Costs Also Rise
The Part A inpatient hospital deductible rises $40 to $1,776 per benefit period. Daily coinsurance for hospital days 61 to 90 goes to $444, and skilled nursing facility coinsurance for days 21 to 100 goes to $222. About 99% of beneficiaries pay no Part A premium.
These deductibles matter most for people choosing between Original Medicare and a private plan. Medigap Plan G covers the Part A deductible and coinsurance but not the $292 Part B deductible; our Medigap vs Medicare Advantage guide compares the two paths.
People who buy Part A because they lack enough work history pay more as well: $328 a month with 30 to 39 work quarters and $597 with fewer than 30.
What To Do Next
- Watch for your SSA notice listing your 2027 premium and any IRMAA.
- File Form SSA-44 if your income dropped after retirement, divorce or a spouse’s death.
- Finish Medicare Open Enrollment choices by December 7.
- Compare 2027 plans in our Medicare Advantage plans by state data.
Read the full figures in the CMS 2027 fact sheet, and follow our Medicare hub for more 2027 changes.